Watch Groups

Meta's Muse Propels Mag-7 Higher Despite Rising Yields

Pension Pulse -

Sean Conlon, Justina Lee and Tobias Burns of CNBC report the Dow jumps more than 470 points Friday; stocks notch winning week despite Treasury yield surge:

U.S. equities rose on Friday as Wall Street wrapped up a volatile week of trading, with a surge in Treasury yields rippling through financial markets.

The S&P 500 climbed 0.51% to close at 7,743.41, while the Nasdaq Composit gained 0.5% to 27,068.72. The Dow Jones Industrial Average advanced 478.64 points, or 0.93% to end at 51,828.62.

Akamai Technologies was a key winner of the session, rising 3% after announcing a multiyear deal with Anthropic.

Also helping sentiment, oil prices slid amid optimism that the Strait of Hormuz could be reopened, as Iran has asked the U.S. to return to the memorandum of understanding from June that failed to end the Middle East conflict. West Texas Intermediate crude futures dropped 2.33% to settle at $92.41 per barrel, while international benchmark Brent crude futures declined 2.14% to $104.32 a barrel.

With the day’s gains, the Dow notched a winning week, up 0.3%. The S&P 500 added 1.2%, while the Nasdaq rose 2%.

That advance was bolstered by technology stocks such as Meta Platforms, which popped nearly 13% on the week amid excitement surrounding its artificial intelligence agent Muse. Information technology rose 3.1%, which was the most of any of the S&P 500′s sectors.

The drama continued in the bond market, where the 10-year Treasury yield climbed to its highest level since 2007, while the 30-year yield reached its highest level since 2004. The two were last seen up slightly at 5.163% and 5.488%, respectively.

This week’s ascent in yields was fueled by hawkish comments from Federal Reserve Governor Michael Barr, persistently high energy prices due to the Iran war, and a hot purchasing managers’ report. Fed funds futures trading suggests a roughly 64% likelihood of a rate hike in October, according to the CME FedWatch tool.

Eric Diton, president of The Wealth Alliance, noted that investor sentiment has been weakening as bond yields have been rising, with bearish sentiment seeing a “sharp” increase from just two weeks earlier. That said, he believes the market has been “incredibly resilient” in the face of the developments, with the S&P 500 and Nasdaq roughly 1% below their recent highs.

“Should rates continue to climb, they should have a larger impact on market performance at some point in the future,” he cautioned.

Meanwhile, traders were monitoring Chinese President Xi Jinping’s visit to the U.S. this week. U.S. Trade Representative Jamieson Greer told CNBC Friday that “a lot more details” on negotiations between the U.S. and China are going to be released Monday.

Treasury Secretary Scott Bessent said earlier in the week that the two countries have agreed to extend their trade truce by two months. 

The big story this week was shares of Meta Platforms (META) surging to a new 52-week high as the company released its new Muse Charm device, which is intended to put it ahead of rivals like OpenAI and Google in AI agents and consumer hardware (read more here):


Look at the weekly 5-year chart above, the never broke below its 200-week exponential moving average. It was a buy near $500 (its 52-week low was $520 a share). And this week it made a new 52-week high before giving up some gains today (the stock is up 32% over the past month).

I didn't need to listen to the talking heads on CNBC to figure out that it was only a matter of time before this stock turns up. At the end of the day, Meta is a cash cow just off Instagram and it seems like all that spending on AI is finally paying off (but they need to demonstrate they're gaining a foothold in the corporate market).

What else? Shares of Microsoft (MSFT) are up nicely today after CEO Satya Nadella said its cloud-based Autopilot is the 'next generation' of enterprise AI (see his comments here).


Microsoft's share price bounced nicely off its 52-week low of $349 and the stock remains in a bullish uptrend despite the lackluster performance over the past month.

More generally, the Roundhill Magnificent Seven ETF (MAGS), which tracks the performance of the “Magnificent Seven,”is back firmly in bullish mode, breaking out and making a new 52-week high:


Also worth noting the iShares MSCI USA Momentum Factor ETF (MTUM), which holds all the top memory chip makers, is turning back up and looking great again:

 Conversely, the Invesco S&P 500 Equal Weight ETF (RSP), which is a broader measure of the market, is turning back down and selling off here as we close the quarter (FOMO kicking in hard):

This is what we have seen all year: either Mag-7 stocks are doing well or the broader market is doing well but rarely, if ever, both are rallying.

Capiche? this is what you need to pay attention to, never mind bond yields back at 2007 levels and all the scary stories about that.

Can the 10-year US Treasury yield touch 6% this year? Sure it can, and I guarantee you every pension fund in the world will be jumping on them at that point, but I doubt yields will back up a lot more here (because already global allocators are buying bonds and unless you have nasty inflation surprises, not going to happen).

In fact, just looking at the iShares 20+ Year Treasury Bond ETF (TLT), which is a price index, I can tell you bonds are starting to look mighty attractive at these levels (but prices can fall further):

There is a point where global pension funds say, "screw this", we are not being compensated enough to take risks in stocks, hedge funds, private equity, private credit, real estate, infrastructure or other risk assets; we are gong to park our money in bonds and wait for a catastrophe to unfold.

We are not there yet but yields backing up like this is offering interesting opportunities in the fixed income markets.

And don't forget, as long bond yields back up, pension liabilities go down a lot because the discount rate goes up. And if stocks hold up, that's great news.

Alright, let me wrap it up with the top-performing US large cap stocks this week (full list here):


And here are the worst-performing US large cap stocks this week (full list here):


And here is my biotech stock of the week, Viking Therapeutics (VKTX):


Do a deep dive here, only a matter of time before this company gets bought out at much higher multiples (read more here but most articles are terrible, look at the top holders and do your own due diligence). 

There are great biotech stocks out there, but I don't get paid enough to share all my secrets.

Below, the CNBC 'Halftime Report' Investment Committee breaks down its reaction to rising Treasurys and what it means for equities.

Also, yields are competing with stocks and the Fed just hiked, but Tom Lee says the market is missing two things: where inflation will be in six months, and which companies actually get stronger as rates rise.

Wages, inequality, and the roots of America’s affordability crisis

EPI -

This piece was originally published in American Educator, the professional journal of the American Federation of Teachers. Read it here. 

Outside of a crisis or recession, Americans’ perceptions of how the country and economy are being managed have never been so negative. Many have attributed this voter unhappiness to a crisis of “affordability.”

It is objectively true that it is too hard for most American families to afford a secure and dignified life. But the word “affordability” leads too many people—including policymakers—to fixate on prices. Affordability is not just about prices; instead, it’s the outcome of a race between incomes and prices.

This is not just economists quibbling. Focusing on prices will lead policymakers to ignore far too much of the useful playing field when thinking about what changes could make life better for working families.

In this article, we make the following arguments:

  • Far too many families are unable to afford a decent economic life.
  • The primary cause is a large increase in income and wage inequality, with incomes and wages for the vast majority of families lagging far behind what they could and should be.
  • This rise in inequality was caused by increasingly unequal “market” incomes (e.g., wages and salaries, returns on investments), while changes in taxes or transfers (e.g., Social Security, Medicare, unemployment insurance) slightly dampened the rise of income inequality.
  • The large rise in income inequality was driven by intentional policy changes that affected typical workers’ leverage and bargaining power in the labor market—and that means they can be reversed.
  • In capitalist economies (like ours), labor markets are inherently tilted toward employers—but historically and globally, broadly shared prosperity has only been achieved when policies that intentionally support workers (like strong unions, adequate minimum wages, and full employment mandates) have provided a countervailing force against employers’ power in labor markets. 
  • Much of the post-1979 period in the United States saw an assault on worker-friendly policies, and this led directly to the rise in inequality and to weak income growth for working families.

Americans’ economic dissatisfaction has real roots

The U.S. economy is the richest in the world, yet the gap between what it could deliver to working families versus what it actually delivers is maddening. This gap can be measured with some precision. Figure A shows inflation-adjusted household income for the middle-fifth of U.S. families between 1979 and 2022, as well as what this growth could have been had it simply grown as fast as average incomes did in this period. 
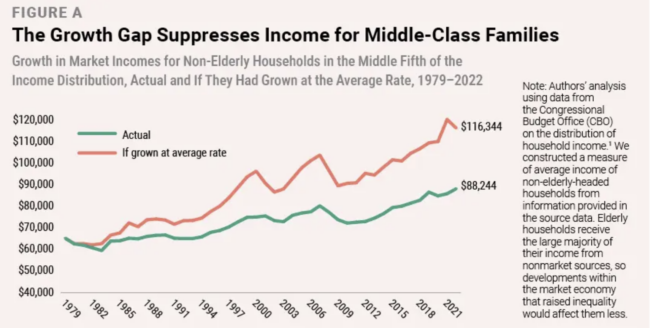
This gap is driven by inequality. Average incomes can only rise faster than incomes at the middle if some groups—the ultra-rich in this case—see strongly above-average growth. This gap between average growth and growth experienced by the middle reached staggering levels by 2022 (the most recent data from the Congressional Budget Office). In that year, inequality’s rise since 1979 deprived middle-income families of an average of $28,100. Life for these families would be far more affordable today if they had this money coming in each year. And that’s well within our grasp. Average income growth is by definition attainable. All that’s needed are policies that ensure income growth is broadly shared, instead of policies that cause staggeringly fast income growth among the top 1% and much slower income growth for working people. 

Figure B shows this inequality another way—charting average annual growth rates for the 1979–2022 period for a number of groups ranked by their position in the income distribution. The strikingly bad news from this figure is that only household groups above the 90th percentile saw income growth that matched or exceeded average income growth. How can more than 90% of households be below average when it comes to income growth? This is possible because the top 5%—and especially the top 1%—saw astoundingly fast growth over this period. 
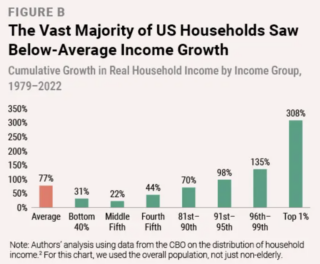
For any given average growth rate, faster growth at the top of the scale must be matched by slower growth at the middle and/or bottom. It is this zero-sum dynamic of inequality, not anything to do with prices, that has been the crushing drag on regular Americans trying to afford a better life over time.

Staggering inequality is a choice

This growth in inequality has been driven by the rules governing markets—rules our elected leaders determine—not by taxes or transfers. Figure A showed the staggering $28,100 gap in market (pre-tax and transfer) income between what families in the middle-fifth actually made in 2022 versus what they could have made had inequality not risen. Figure C shows how large this gap is after the federal government gets involved on the tax and transfer side of the equation. 
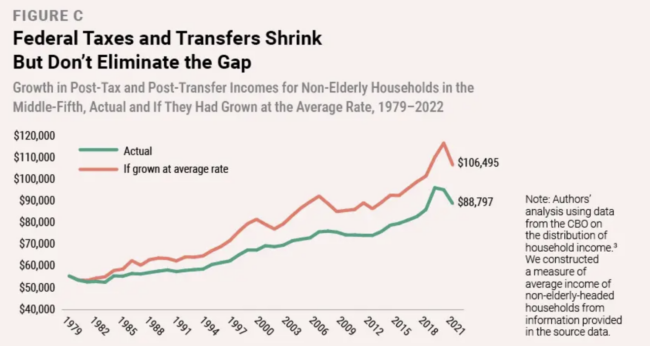
Taxes obviously reduce incomes, but transfers (social insurance like Social Security and income support payments like unemployment insurance) raise incomes. For the middle-fifth of US households, this effect is largely a wash—their current income levels in Figures A and C are very similar. But because the United States still has a progressive federal tax system (though not as progressive as we would like), the rise of inequality in this post-tax and transfer data is slightly muted—i.e., federal taxes and transfers shrink the gap somewhat. By 2022, the annual gap after accounting for federal taxes and transfers is $17,698—still a sum of money that would be transformative for American families.

Essentially, federal taxes and transfers undid roughly one-third of the rise in income inequality, allowing rich households to pocket roughly two-thirds of their gains.*

This rise in inequality was overwhelmingly driven by an intentional, multipronged policy campaign to suppress wages that was undertaken by shareholders, other capital owners, and corporate executives, with policymakers greasing the skids along the way.4 The primacy of wage suppression can be seen in Figure D, which compares the economy’s potential to pay higher wages and incomes with the actual hourly pay of typical workers in the United States. 
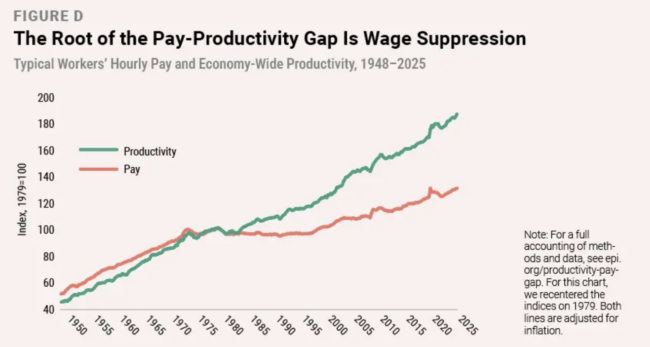
We measure the economy’s potential to pay higher wages by productivity, which is the output and income generated in the economy in an hour of work on average. And we define typical workers’ pay as the wages and benefits of workers in production and nonsupervisory positions, a group that constitutes over 80% of the economy’s private-sector workforce, excluding higher-wage managers and executives. As you see in the figure, in the three decades after World War II, productivity and pay mostly moved roughly in tandem, with typical workers’ pay rising 83% as fast as productivity. After 1979, these lines diverge sharply, with workers’ pay rising only about 43% as fast as productivity. 

If typical workers’ pay had risen in line with productivity growth in the years since 1979, their hourly pay would be 43% higher today. For a full-time, full-year worker making the median wage, this would constitute annual wages that are almost $23,000 higher.5 Where did that $23,000 go? Instead of paying workers more as their productivity rose, corporate executives, other already highly paid professionals, and shareholders captured those gains for themselves.

This growing gap between what shows up in typical workers’ paychecks and benefits versus the overall income being generated in the economy is the root story of American inequality and of today’s affordability crisis.

This pay-productivity gap can be decomposed into two parts: the portion driven by rising inequality in “labor” income (income earned from work), and the portion driven by a shift from labor income to “capital” income (income from investments, like when a stock increases in value). Growing inequality within labor incomes—earnings growing much faster among high-paying jobs than among middle- and low-paying jobs—accounts for almost 80% of the gap. The remaining 20% is accounted for by a shift from labor income to capital income.6 Below we say a bit more about each of these.

Rising inequality of labor incomes

The larger factor in the rise of overall income inequality is the growing inequality within labor incomes. This often surprises people, who assume the story of rising inequality is mostly one of the profits of rich corporations rising while most of their workers are left behind. It’s true that most workers in these corporations do not benefit, but the powerful employees who do prosper—CEOs and other executives—receive astronomical salaries that are classified as labor income in economic data, and these inflated executive salaries do cut into corporate profits. 

In addition, below the stratospheric level of corporate managers at large companies, there is a stratum of workers in medicine, legal services, and finance who command huge salaries. It’s not a large group of people, but the rise in their pay has been extreme. Figure E highlights this radical inequality within labor incomes, showing annual earnings of various wage groupings. (To keep the figure legible, pre-1979 data are not shown.) Prior to 1979, wage growth among very high wage workers—those in the top 10%, the top 1%, and the top 0.1%—was roughly in line with wage growth for the vast majority (i.e., for the bottom 90%). But between 1979 and 2023, cumulative growth in average annual earnings for the bottom 90% of workers was 44%, compared with 133% for the top 1%. For the top 0.1%, this growth was 354%—so high it doesn’t fit in the figure.
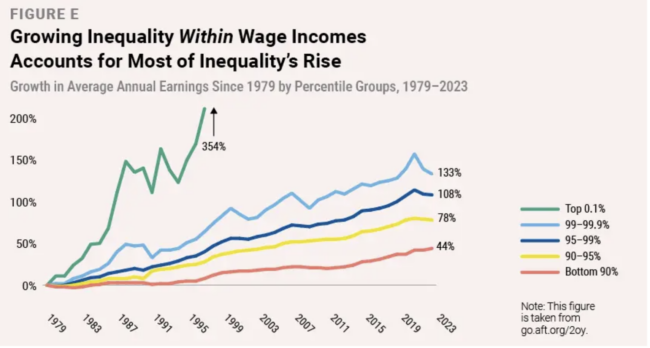
Given that labor income remains the large majority of all income generated in the economy, this huge rise in inequality within labor incomes is a key driver of the economy-wide march to greater inequality. Workers at the top of the wage scale were largely able to insulate themselves from the campaign of wage suppression launched by corporate owners. Of course, some of them were active participants in this campaign and got a significant cut of its benefits (think CEOs and lawyers for union-busting law firms). But the vast majority of workers (roughly 90%, as we see in Figure B) were on the losing side of this wage suppression campaign and found their wages falling far behind the economy’s potential to deliver strong and sustained wage growth. 

In some ways, the influence of rising inequality within labor incomes might be underestimated. For decades, U.S. tax policy has levied lower tax rates on capital income than labor income, and a great deal of capital gains escapes taxation entirely due to loopholes. 

Many of the same people who have been privileged enough to insulate themselves from wage suppression are also privileged enough to have excellent accountants who can make their incomes appear in whatever form results in the lowest taxes.7 For example, CEOs are overwhelmingly paid with “performance-based” measures, which means measures tied to the value of their companies’ stock prices. Twenty years ago, the large majority of this stock-based pay for CEOs came in the form of stock options, which are contracts that give the CEO the right (but not the obligation) to buy shares of stock at a set price. If the market price went above this set price, CEOs could exercise these options and pocket the difference as pay. The gains from exercised stock options are recognized by the IRS as labor income, taxed accordingly, and classified in data as labor income. But over the past two decades, there has been a pronounced shift in the stock-based pay of CEOs away from stock options and toward the outright granting of stock. In this case, CEOs are not given a right to buy shares at a preferential price; they are simply given shares.8 What’s important for the split between capital and labor incomes is that these non-option forms of stock-based compensation are far less likely to be captured in measures of wage incomes. So this tax evasion strategy artificially depresses estimates of labor income in the economy.

The shift from labor to capital incomes

While most of the pay-productivity gap stemmed from the rising inequality within labor earnings discussed above, a nontrivial portion of this gap stemmed from a shift in overall income from labor to capital. This goes far beyond the tax avoidance trick described above for CEO compensation—including paying regular working people less so that shareholders get more. If, for example, a corporation were able to suppress its workers’ pay while raising customers’ prices and/or cutting what it paid suppliers (which generally means those suppliers paying their workers less), it would earn higher profits. By successfully suppressing wages to boost profits, American corporations have made their stock more valuable. Imagine an investor buys $100 in company stock with the expectation of an annual return of $5. If the company undertakes a successful campaign of wage suppression that boosts annual returns to $10, many other investors will buy company stock—bidding up share prices.

So even though this labor-to-capital shift in overall income is the smaller player in generating overall income inequality, it still had profound effects on American economic life. Estimates indicate that anywhere from 40% to nearly 100% of the entire nominal gains in the U.S. stock market since 1989 can be attributed to this shift of income from workers to capital owners.9

The rise in US stock prices in recent decades is a key driver of another kind of economic inequality: inequality of wealth.† One of the primary sources of wealth, the ownership of corporate equities (e.g., shares of stocks), is incredibly concentrated; the top 10% of households own about 85% of all corporate equities, and the top 1% own nearly 40%.10

The concentration of corporate equities combined with the role of wage suppression in making these equities far more valuable leads to a clear implication: The wage suppression of recent decades is not just by far the biggest driver of the rise in income inequality; it is also by far the biggest driver of the rise in wealth inequality. Most of the rise in wealth inequality in recent decades has been the outcome of an intentional transfer away from workers to the top. 

Labor markets are not fair

This rise in inequality in recent decades has attracted much attention from researchers—along with everybody else struggling to pay for groceries and keep the lights on. For a long time, economists’ role in the debate over inequality was to look for reasons why well-functioning, competitive markets could generate lots of inequality. This often led to explanations that essentially blamed workers for the outcomes. The argument was that the fair and competitive labor market had spoken and that these workers were falling behind because their skills and efforts had been found wanting. The precise failure identified was often workers’ alleged inability to adapt to the quickening pace of technological change in the economy. 

But the evidence supporting this view of inequality driven by apolitical forces working through fair and competitive markets was incredibly thin.11 That led many researchers to examine whether labor markets are by their very nature tilted against workers, making it very difficult to secure regular raises that match overall economic growth. 

There is ample evidence for this view—that excess employer-side power makes labor markets generally unfair and inefficient, and that truly fair, competitive labor markets are the exception, not the rule. For example, many employers, and particularly those of low- and moderate-wage workers, rarely if ever negotiate pay; instead, they post take-it-or-leave-it wage offers.12 And when a given employer lets its wages lag behind those of potential competitors, workers’ exit from the lower-wage firm is far less common than would be predicted under truly competitive labor markets (where employers robustly compete for workers).13

This employer-side power is rooted in many obvious factors in real-world labor markets that make it hard for workers to effectively search for better jobs and, therefore, force employers to compete over them. These include things like lack of information about wages and benefits offered by other employers, transportation restrictions that require workers to look for jobs only in places near their homes or public transit nodes, and child care considerations that require a job’s location be compatible with picking up kids at a regular time, along with many other factors. 

Another barrier to competition is the obvious fact that in the short run, most employers need the income a new worker would generate for their business far less than most workers need the income from a job. In a jobsite of 100 workers, having a month go by understaffed by a single worker reduces business income by roughly 1%. In a household with a single worker, having a month go by without a job reduces income by essentially 100%. 

Employers exploit these barriers to employees finding better options by “marking down” wages below what would be necessary for employers to attract and retain workers in competitive labor markets. These markdowns can be large enough to push workers’ pay well below the value they produce for the employer (i.e., below the “market clearing” wage). This makes them not just unfair, but inefficient—a drag on economic growth. 

Key policy choices that led to rising inequality 

Having realized the role of employers’ power in determining labor market outcomes, the importance of specific policies is magnified. For example, before the 1990s, many economists were extremely skeptical that minimum wages could do much good in raising wages without steep downsides like job loss. Why? Because they erroneously used models of competitive labor markets. 

But more accurate models that include employers’ power reveal significant room to raise minimum wages without generating job losses. The evidence over the past 30 years has been highly persuasive that minimum wages could be much higher than they were in the 1980s and 1990s without causing job losses and that the benefits for low-wage workers would be large.14

The period of rising inequality since 1979 was one of profound institutional change in labor markets. The federal minimum wage, for example, lost 35% of its value between 1979 and 2025 as legislative inaction (i.e., not raising it) allowed it to be battered into irrelevance by inflation.15 This was also a period that saw a pronounced acceleration in the decline of unionization rates of American workers.16 It was a time when high levels of unemployment were tolerated by policymakers for extended periods in the name of fighting inflation.17 And it was a time when increasing integration between the rich United States and a poorer global economy was done on terms that were written by and for corporate interests.‡

Several years ago, researchers at our organization, the Economic Policy Institute, reviewed the research on how much specific policy choices likely contributed to growing inequality. Adding together the impacts of the changes like those listed above could easily explain the lion’s share of the rise in inequality since 1979.18

For example, one key policy change was the practical abandonment of the Federal Reserve’s full employment mandate. By law, the Fed is supposed to pursue both stable inflation and full employment (which means trying to keep unemployment as low as is consistent with stable inflation). But between 1979 and 2007 (right before the Great Recession), the Fed largely acted as if it did have a mandate to pursue stable inflation but did not have one to pursue full employment. 

After the Great Recession, the Fed admirably reversed course and tried to push the economy back to full employment, but its tools proved too weak given the magnitude of the shock. In such situations, fiscal policy—taxes and spending—should be used aggressively to restore full employment. But in the 2010s, political gridlock and excess caution kept policymakers from doing this, and much of that decade was plagued by excess unemployment. 

Excess unemployment does not just leave willing workers locked out of jobs. It also saps the ability of still-employed workers to demand raises. For nonunion workers, their chief leverage for getting wage increases is threatening to quit. This threat is only credible when unemployment is low. Consequently, the too-high unemployment rates for most of the period from 1979 to 2019 were a drag on wage growth. In our estimates, too-high unemployment may well have explained nearly a third of the entire pay-productivity gap over that period19—not to mention the devastation it wrought for millions of families.

Another key policy change was the failure to keep the playing field level between workers looking to organize and join unions and the employers who wanted to stop them. The National Labor Relations Board is supposed to safeguard this right, but its tools have proved too weak in the face of fierce employer opposition to unions, and policy changes to strengthen these tools have consistently been blocked. The results of throttling the growth of new unions have been profound; our estimates are that declining unionization likely explains a quarter of the pay-productivity gap since 1979.20 Crucially, the decline in unionization did not just hurt workers who otherwise would have been unionized. By far the biggest of the wage-suppressing effects of deunionization has been on the broad pool of nonunion workers. As unions lose strength, they stop being able to set industry-wide pay standards that even nonunion employers feel like they have to meet to avoid hemorrhaging employees. 

The wage-depressing effect of trade flows from poorer nations—flows encouraged by the corporate-led trade agreements the United States has signed in recent decades—can likely explain another 10 to 15% of the pay-productivity divergence since 1979.21

The wrong incentives

Tolerating excess unemployment, throttling workers’ ability to join unions, failing to update the minimum wage as costs rise, and signing corporate-friendly trade agreements were some of the many instruments of wage suppression undertaken and abetted by policymakers in recent decades. At the same time, choices legislators made on tax policy boosted the incentive for capital owners and corporate managers to aggressively use these instruments to increase their wealth. 

When ultra-high incomes and corporate profits are taxed at high (i.e., appropriate) rates, the incentives for powerful individuals to rig the rules of markets to suppress regular workers’ wages are much smaller. Key research shows that this incentive effect is real and powerful. For example, across countries, the larger the tax cuts on the rich enacted in recent decades, the greater the increase in pre-tax inequality.22 And, the lower the top tax rates for individuals, the higher the levels of pre-tax CEO pay.23 High taxes reduce the benefits of rule-rigging, so cutting taxes increases rule-rigging. This means that raising taxes on the richest households and corporations results in new revenue and more equal pre-tax incomes. But from the mid-1970s, tax rates for high-income households and corporations have been cut steadily and deeply in the United States, reducing both tax revenues and wages for working people.

Income inequality, not high prices, is behind the affordability crisis

We opened this article with a claim that affordability is the outcome of a race between income and prices. Our long walk through the economics and history of recent American inequality highlights that intentional policy choices have deprived typical households of income they could have otherwise claimed. Without this inequality, a middle-income household today would have tens of thousands of dollars more per year—and this would obviously make affording a decent life much easier. 

But some might wonder if we have still given prices short shrift in how much they contribute to affordability challenges. We don’t think so, for a number of reasons. We sketch three of them here.

First, all of the income, wage, and productivity statistics we have included in this article have been real (i.e., they have been adjusted for the impact of inflation). And it is unambiguously true that real (inflation-adjusted) incomes are the proper way to measure living standards and economic possibilities for households. 

Getting distracted by price growth while missing what’s happening with income will lead to wrong conclusions about economic performance over even relatively recent periods of time. Figure F compares two periods, both starting one year before a deep recession struck and then running five years: 2007–2012 and 2019–2024. In the first period, inflation averaged 1.8%, while in the second it ran more than twice as fast at 4.2%. Yet real (inflation-adjusted) wage growth for low- and middle-wage workers was far faster in the second period. For the lowest-wage workers, real wages fell by 2.1% in the first period but rose by 15.3% in the second. For workers in the middle of the wage scale, real wages fell by 1.5% in the first period but rose by 5.8% in the second. 
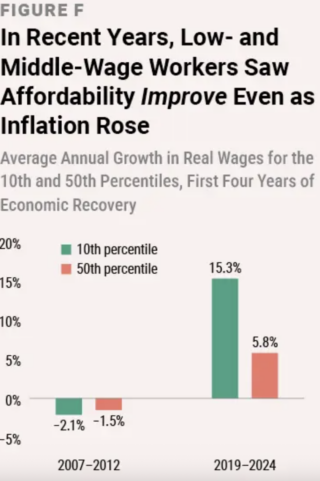
Over very short periods of time (one to two years), it is true that a rapid spike in prices tends to drive down real incomes and wages. But over any longer period (even as short as three to five years), assessing how the economy is doing for typical families rarely bears much relationship to price growth.

Second, even when researchers adjust for inflation differently at different parts of the wage and income distribution, the impact is modest. Such measures account for things like lower-income families spending a higher share of their income on rent and groceries and a lower share on vacations. But there are surprisingly small differences in overall price growth faced by families at different income levels. For example, from 2019 to 2025, when the price of housing and groceries was on peoples’ minds for good reasons, the inflation rate faced by the bottom 40% of households was just 0.2% higher than for the top 20% of households.24 In short, the growth in prices faced by different groups varies far less than the growth of their incomes and wages. 

Third, a key insight in assessing affordability debates is that one person’s cost is another person’s income. If the cost of a pound of coffee doubles from $10 to $20, this constitutes $10 of additional income that somebody is getting. Perhaps the coffee grower or the shipper or the grocery store shareholders or the CEO or the cashiers or some other link in the supply chain is getting an extra $10 (or several of them are getting some slice of it). This means that rapidly rising prices cannot result in less income overall, so they are highly unlikely to actually make an entire economy poorer. Instead, the groups that face only the price increase lose out while groups receiving the extra income win. 

This fact that every price is an amalgamation of various income streams also means policymakers can more usefully target wage and income policies rather than price policies. Again, my bill at the grocery store pays for the wages of cashiers, the pay of the company CEO, the dividends to shareholders, the payments to suppliers, and more. Even if we’re unhappy about this grocery bill, we likely don’t want all of those price components to get squeezed. We probably want the wages of cashiers to rise while hoping to rein in CEO pay and shareholder dividends. Policies that only look to restrain prices—price controls, for example—make no such distinction, so we don’t know who in the grocery supply chain will bear their burden (though we can guess it’s more likely to be the cashiers than the CEO). But if we raise minimum wages, change labor law to allow more widespread unionization, and raise taxes on the ultra-rich and on corporate profits, we have a very good idea of which incomes will be boosted and which will get squeezed.

Creating a fairer economy

It is deeply depressing that intentional policy acts led to the enormous rise in inequality that is making life so much harder for so many people. If tens of millions of American households had tens of thousands of extra dollars in their bank accounts each year while billionaires had significantly less money, the country would be a much better and happier place.

What brings us hope is the knowledge that because the rise in inequality was not the inevitable outcome of a modern economy, it can be halted and reversed. Today’s workers have the skills and abilities needed to support much higher incomes with no loss in efficiency or employment—if we change policy to give them these higher wages. This is excellent news. Of course, many of today’s elected leaders—and their donors—have little interest in reducing inequality, so the road ahead is long. But the foundational ingredients for a fairer and more efficient economy are clear: 

  • Keep unemployment rates low for long periods of time and fight recessions fiercely when they inevitably occur. 
  • Restore the right to organize new unions and bargain collectively. 
  • Raise minimum wages, including the federal minimum wage. 
  • Enact rules for the global economy that support healthy wage growth, not just healthy corporate profits. 
  • Crush the incentive to rig the rules of the economy by raising taxes significantly on ultra-rich households and corporations. 

The details on how we create a fairer economy are more complex—and they do matter! But understanding that the affordability crisis facing American families is overwhelmingly an inequality crisis is a necessary and useful place to start.

*Since this analysis goes through 2022, it does not include the tax or benefits cuts (including to Medicaid and the Supplemental Nutrition Assistance Program) in the One Big Beautiful Bill Act that President Trump signed into law in July 2025. These will further increase inequality.

†Wealth is the value of a person’s assets (e.g., the equity in their home, stocks and bonds in their retirement accounts, or their baseball card collections) minus the value of their debts.

‡For details, see “A Trade Policy That Puts Working Families First.” 

Footnotes

1. Congressional Budget Office, The Distribution of Household Income, 2022 (January 2026), cbo.gov/publication/61911.

2. Congressional Budget Office, The Distribution.

3. Congressional Budget Office, The Distribution.

4. For a much deeper dive into the specifics of this policy campaign of wage suppression, along with empirical assessments of how much it cost American families, see L. Mishel and J. Bivens, “Identifying the Policy Levers Generating Wage Suppression and Wage Inequality,” Economic Policy Institute, May 13, 2021, epi.org/unequalpower/publications/wage-suppression-inequality.

5. The median wage for U.S. workers in 2025 was $25.67. This (and a lot more) can be found at data.epi.org. Multiplying this median wage by 0.43 and then by 2,080 (hours worked by a full-time/full-year worker) yields the $23,000 figure.

6. Earlier estimates of how much inequality within wages contributed to the pay-productivity gap can be found here: L. Mishel, “Growing Inequalities, Reflecting Growing Employer Power, Have Generated a Productivity–Pay Gap Since 1979,” Working Economics Blog, September 2, 2021, epi.org/blog/growing-inequalities-reflecting-growing-employer-power-have-generated-a-productivity-pay-gap-since-1979-productivity-has-grown-3-5-times-as-much-as-pay-for-the-typical-worker. The easy way to update this (which we did for this report) is to compare productivity with growth in overall average compensation of American workers since 1979. This overall average compensation rose by roughly 76% since 1979. Given typical workers’ pay growth of just under 30%, this means that 46% (76% minus 30%) of the divergence between typical workers’ pay and productivity is a difference between typical workers’ pay and average pay.

7. See here for an estimate of how much of today’s reported capital incomes would be more properly classified as the returns to work (i.e., labor incomes): A. Eisfeldt, A. Falato, and M. Xiaolan, “Human Capitalists,” NBER Working Paper no. 28815, National Bureau of Economic Research, April 2022, nber.org/papers/w28815.

8. For more on CEO pay levels and their composition, see J. Bivens, E. Gould, and J. Kandra, “CEO Pay Has Skyrocketed Since 1978,” Economic Policy Institute, September 25, 2025, epi.org/publication/ceo-pay.

9. For this estimate, see D. Greenwald, M. Lettau, and S. Ludvigson, “How the Wealth Was Won: Factor Shares as Market Fundamentals,” Journal of Political Economy 133, no. 4 (April 2025): 1083–1132; and A. Atkeson, J. Heathcote, and F. Perri, A Macroeconomic Perspective on Stock Market Valuation Ratios (Federal Reserve Bank of Minneapolis, Research Division, January 2026), minneapolisfed.org/research/sr/sr682.pdf.

10. See Table 10 in: E. Wolff, “Household Wealth Trends in the United States, 1962 to 2019: Median Wealth Rebounds… but Not Enough,” NBER Working Paper no. 28383, National Bureau of Economic Research, January 2021, nber.org/system/files/working_papers/w28383/w28383.pdf.

11. For a much deeper dive into the weakness of claims that inequality was driven by technology rewarding skilled workers and penalizing less-skilled workers, see J. Schmitt, H. Shierholz, and L. Mishel, Don’t Blame the Robots: Assessing the Job Polarization Explanation of Growing Wage Inequality (Economic Policy Institute, November 19, 2013), epi.org/publication/technology-inequality-dont-blame-the-robots.

12. One study found that roughly 75% of low-wage jobs were ones where employers made take-it-or-leave-it posted offers: R. Hall and A. Krueger, “Evidence on the Incidence of Wage Posting, Wage Bargaining, and On-the-Job Search,” American Economic Journal: Macroeconomics 4, no. 4 (October 2012): 56–67; and R. Hall and A. Krueger, “Evidence on the Determinants of the Choice Between Wage Posting and Wage Bargaining,” NBER Working Paper no. 16033, National Bureau of Economic Research, May 2010, nber.org/system/files/working_papers/w16033/w16033.pdf.

13. For evidence on how nonresponsive worker quits are to wage cuts relative to predictions of competitive markets, see A. Dube, L. Giuliano, and J. Leonard, “Fairness and Frictions: The Impact of Unequal Raises on Quit Behavior,” American Economic Review 109, no. 2 (February 2019): 620–63.

14. For a comprehensive review of this evidence, see D. Cengiz et al., “The Effect of Minimum Wages on Low-Wage Jobs,” Quarterly Journal of Economics 134, no. 3 (August 2019): 1405–54.

15. Economic Policy Institute, “Minimum Wages: Real Minimum Wage (2025$),” 2026, data.epi.org/minimum_wage/minimum_wage_levels/line/year/national/real_minimum_wage_2025/overall?timeStart=1938-01-01&timeEnd=2025-01-01&dateString=1979-01-01&highlightedLines=overall.

16. P. Romero and J. Whittaker, A Brief Examination of Union Membership Data (Library of Congress, June 16, 2023), congress.gov/crs-product/R47596; and H. Meyerson, “Economic Inequality Is Undermining America: Worker Solidarity Will Build a Better Future,” AFT Health Care 3, no. 2 (Fall 2022): 33–36.

17. S. Galan, “Monthly Federal Funds Effective Rate, Unemployment Rate and Inflation Rate in the U.S. During Paul Volcker’s Terms as Federal Reserve Chairperson from 1979 to 1987,” Statista, October 2022, statista.com/statistics/1338105/volcker-shock-interest-rates-unemployment-inflation/?srsltid=AfmBOoqoXQ4yTpqiSJMevwNFbnNGEETrwhlltEeVrJuA1rThyYCBBkFl.

18. Mishel and Bivens, “Identifying the Policy Levers.”

19. J. Bivens, “Focus on the Boom, Not the Slump—the Fed’s New Policy Framework Needs to Stop Cutting Recoveries Short,” Working Economics Blog, Economic Policy Institute, June 18, 2019, epi.org/blog/focus-on-the-boom-not-the-slump-the-feds-new-policy-framework-needs-to-stop-cutting-recoveries-short-epi-macroeconomics-newsletter.

20. Mishel and Bivens, “Identifying the Policy Levers.”

21. Mishel and Bivens, “Identifying the Policy Levers.”

22. A. Fieldhouse, Rising Income Inequality and the Role of Shifting Market-Income Distribution, Tax Burdens, and Tax Rates (Economic Policy Institute, June 14, 2013), epi.org/publication/rising-income-inequality-role-shifting-market.

23. J. Bivens, “Using Tax Policy to Restrain CEO Pay: Best Practices and Smart Alternatives,” Economic Policy Institute, December 13, 2023, epi.org/publication/using-tax-policy-to-restrain-ceo-pay-best-practices-and-smart-alternatives.

24. Authors’ analysis of data obtained from: Federal Reserve Bank of New York, “Economic Heterogeneity Indicators (EHIs),” 2026, newyorkfed.org/research/economic-heterogeneity-indicators.

OMERS Promotes Laura Lenz to Lead Ventures Amid Canada-First Push

Pension Pulse -

Sean Silcoff of The Globe and Mail reports OMERS promotes Laura Lenz to lead venture capital unit:

Ontario Municipal Employees Retirement System has appointed Laura Lenz to head its venture capital arm, the fourth person to hold the job in just over three years, while signalling a continued commitment to backing Canadian technology founders.

Ms. Lenz, a veteran early-stage capital investor who joined OMERS Ventures in 2019 and oversaw its Canadian investments, replaces Saar Pikar, who left in July after just one year on the job to lead Kensington Capital Partners Ltd. He in turn had replaced Michael Yang, who departed two years after replacing Damien Steel, who left in 2023 to lead climate technology startup Deep Sky Corp.

“We have a fantastic track record in Canada, and I’m excited to continue building,” said Ms. Lenz, who started her career as an associate with BMO Capital Markets before taking on investor roles at EdgeStone Capital Partners, MaRS Investment Accelerator Fund and Geoff Beattie-led Generation Ventures. “I know the people, I know our portfolio, I know our strategy.”

OMERS private capital head Michael Block said in an interview: “We have tremendous confidence in her and her whole team. She is very thoughtful and conscious about risk. She’s built a great network of relationships with founders in Canada and has a great reputation.”

OMERS Ventures started in 2011 when then-CEO Michael Nobrega brought on John Ruffolo to back promising Canadian tech entrepreneurs. The timing was ideal. While the Canadian venture capital industry was reeling following the retreat of institutional investors during the 2008-09 credit crisis, the tech startup world was rife with opportunity, as smartphones, cloud computing and artificial intelligence proliferated.

OMERS Ventures made early bets on future Canadian champions including Shopify Inc., Xanadu Quantum Technologies Ltd. and Hopper Inc. It expanded to Britain and the United States and began managing third-party capital before Mr. Ruffolo departed in 2018.

But OMERS Ventures’ relative prominence in the ecosystem faded as other domestic tech financiers including Georgian, Inovia Capital and Radical Ventures amassed billions of dollars in assets.

The information technology sector entered a prolonged slump in 2021 – with the exception of artificial intelligence and quantum computing – and the rise of AI-powered companies weighed on valuations of cloud-software companies, including many held by OMERS Ventures. OMERS this year sustained a nine-figure loss after TouchBistro Inc., which OMERS Ventures and OMERS Growth had backed heavily in the 2010s, was bought by Constellation Software for $100-million.

By then OMERS Ventures had stopped investing in Europe to focus primarily on Canada and shed much of its staff. Today it has four partners including Ms. Lenz, five associates and a principal.

The changes stem from a broader review of OMERS’s private-equity business, which has pivoting toward more investing through third-party funds and as a co-investment partner, with a North American focus. OMERS has also stopped making new growth-stage investments in more mature tech companies through a separate group.

At the same time, Ontario Teachers’ Pension Plan has amassed more than $25.9-billion in investments by financing some of the hottest technology names in the world through its venture growth arm TVG, including Anthropic PBC, Space Explorations Technology Corp. (SpaceX), Databricks Inc. and legal AI software vendor Harvey AI Corp.

OMERS Ventures, which has about $2-billion allocated to venture investments – roughly 1 per cent of the pension giant’s assets – has made four investments in each of the past three years. It has continued to back high-profile emerging Canadian tech names, including Cohere Inc., Waabi Innovations Inc., Float Financial Solutions Inc. and Dominion Dynamics. Its stake in Xanadu, despite a recent selloff, is still worth more than US$200-million –a sizable gain given it invested less than US$30-million for its stake.

Ms. Lenz said OMERS Ventures’ refocusing on Canada has worked out. “It’s where our network is. It’s where our best performing companies are. We have a lot of opportunity here,” she said. She said OMERS is looking to invest $5-million to $15-million per company, focusing on rapidly expanding AI-first businesses led by “ambitious founders that have a global market opportunity.”

Mr. Block said OMERS Ventures would continue “the same direction of travel” under Ms. Lenz and that the pension fund doesn’t plan to increase its allotment to venture capital. But, he added, “we’re open minded. We look at opportunities as they come. We just see a really good opportunity to focus on what we’re focused on.” 

Lauren Bailey of Markets Group also reports OMERS taps Laura Lenz to lead Ventures amid Canada-first push:

The Ontario Municipal Employees Retirement System (OMERS) has appointed Laura Lenz managing director and head of its Ventures platform as the fund doubles down on backing Canadian technology companies and founders.

Her appointment comes as OMERS more broadly increases its exposure to Canada. The pension fund, which had C$151.6 billion in net assets as of June 30, has committed to making at least C$10 billion in new Canadian investments over five years and deployed an additional C$1 billion into Canadian equities during the first half of 2026.

“[Lenz] brings the experience, judgment and deep understanding of founders needed to lead OMERS Ventures into its next chapter,” said Michael Block, head of private capital, in a press release. “She will build on the strength of an experienced team with a continued focus on supporting high-potential companies, deploying capital with conviction and helping founders build businesses that can scale globally.”

Lenz has been with OMERS Ventures for seven years and has worked in venture capital since 2004. She brings experience across venture capital, growth investing and company building, along with a strong understanding of founders, technology companies and the Canadian innovation ecosystem.

The appointment builds on leadership changes OMERS implemented within its Ventures group last year, when Lenz was promoted from partner to managing director as the platform increased its focus on Canada while continuing to pursue selective opportunities in the U.S.

Founded in 2011 with its first investment in Toronto-based Wave, OMERS Ventures has backed 46 Canadian companies, including Shopify, Xanadu, D2L, Float, Hopper, Jobber, League, OneVest, Solink, Wave Accounting, Wattpad and Waabi. More recently, it backed Cohere and Dominion Dynamics, participating this year in Dominion Dynamics’ C$139 million Series A funding round.

Under Lenz’s leadership, OMERS said the platform’s focus will continue to be Canada first, backing ambitious founders and category-defining companies while using OMERS’ global network, scale and flexible capital to help founders access capital, customers and growth opportunities.

In a LinkedIn post announcing her appointment, Lenz said OMERS Ventures has two additional investments that have yet to be publicly announced. She grouped those investments alongside Cohere and Dominion Dynamics as examples of where the platform sees the next generation of important companies emerging: at the intersection of artificial intelligence, infrastructure and software.

Lenz also outlined the platform’s investment strategy going forward, noting OMERS Ventures plans to target exceptional early-stage companies with initial investments of C$5 million to C$15 million and remain a meaningful partner as those businesses scale.

“We are a venture platform with the ability to invest early, support companies through scale and bring more than capital to the table,” Lenz wrote.

Today, OMERS Ventures announced the appointment of Laura Lenz as Managing Director, Head of Ventures, backing the next generation of global companies:

OMERS Ventures today announced that Laura Lenz has been appointed Managing Director, Head of Ventures, marking the next chapter for the platform as it continues to back ambitious founders building globally competitive companies from Canada and beyond.

“Laura brings the experience, judgment and deep understanding of founders needed to lead OMERS Ventures into its next chapter,” said Michael Block, Head of Private Capital. “She will build on the strength of an experienced team with a continued focus on supporting high-potential companies, deploying capital with conviction and helping founders build businesses that can scale globally.”

Lenz has been with OMERS Ventures for seven years and has worked in venture capital since 2004. She brings deep experience across venture capital, growth investing and company building, along with a strong understanding of founders, technology companies and the Canadian innovation ecosystem.

“Venture is ultimately a people business,” said Lenz. “The best outcomes come from trust, judgment, conviction and partnership. My priority is to build on that foundation: creating an environment where different perspectives are valued, individual conviction is encouraged and our collective standard remains high.”

Founded in 2011 with its first investment in Toronto-based Wave, OMERS Ventures has been an early and long-standing supporter of Canadian companies, founders and the broader venture ecosystem. Since inception, OMERS Ventures has backed 46 Canadian companies, including Shopify, Xanadu, D2L, Float, Hopper, Jobber, League, OneVest, Solink, Wave Accounting, Wattpad, Waabi, with more recent investments in Cohere and Dominion Dynamics.

Under Lenz’s leadership, OMERS Ventures’ focus will continue to be Canada first: backing ambitious founders and category-defining companies, while using OMERS global network, scale and flexible capital to help founders access capital, customers and growth opportunities.

“The ambition has been here in Canada,” said Lenz. “What is changing is our willingness to build around it. At OMERS Ventures, our part is clear: back exceptional founders early, bring meaningful capital and conviction, use the full strength of the OMERS network where it can help, and support those founders in building companies that can compete with anyone, anywhere.”

As part of OMERS, one of Canada’s largest pension plans, OMERS Ventures is able to connect founders with institutional expertise, global relationships and sector knowledge across markets and geographies. That platform advantage supports the team’s goal of helping companies scale while creating long-term value for OMERS members, and aligns with OMERS broader commitment to invest $10 billion more in Canada over approximately the next five years across asset classes.

OMERS Ventures sees a strong opportunity set in Canada, particularly in areas where AI is creating or reshaping markets, including defence technologies, physical AI, and vertical AI platforms built for specific industry workflows. Next week, OMERS Ventures will host its annual AI Assembly Summit, bringing together leading Canadian and international investors, founders and industry experts to discuss how artificial intelligence is reshaping venture capital, infrastructure, defence, robotics and the broader investment landscape.

Alright, big announcement at OMERS Ventures which has seen a lot of turnover at the helm recently after Saar Pikar, the former head, left the pension fund in July to become president of Kensington Capital Partners Ltd.

That move marked the third time in three years that the OMERS Ventures unit has changed hands. Damien Steel left in 2023. Michael Yang, its most senior venture capital leader, followed two years later. 

Hopefully, Ms. Lenz will stick around longer than her predecessors. She has the experience and judgment and an interesting background with great and authentic perspective:

Growing up, the dinner table was my first conference room. My dad's investment banking background merged with my mom's nursing career, and our family’s passion for art, created the foundation for a rich tapestry of conversation. From an early age I was captivated by financial narratives.

‍I also loved languages. I started teaching myself Spanish in 4th grade and Japanese in 7th grade. My love of languages would lead me to spending time studying or working in Mexico,Tokyo and Peru at various points in my life, ensuring that today I look at most things through a truly global lens. My fascination with Japan was directly linked to my martial arts practice. I still train regularly today and currently hold black belts in Karate and Tae Kwon Do. Not only did martial arts instill in me a deep sense of respect for the role of health in my ability to succeed, but it taught me a level of discipline I still draw upon today.

‍After a finance-focused undergrad and working in Tokyo and New York City, I discovered my love for private markets - and venture capital in particular - at Edgestone in 2004. It was one of Canada's few early-stage tech funds at the time. And at $104M it was one of the biggest! Working alongside two operators, I honed my investing skills, learning that respect and humility are just as vital as vision and strategy.

While in banking, I was involved in a significant IPO at the time – 724 Solutions – it was a payments engine and soared to a market cap larger than the Bank of Montreal (where I worked at the time). It was quite a journey and helped me to understand a bubble early in my career. 

‍Today, I am most interested in looking at companies operating at the intersection of fintech and commerce - I call it financial value exchange. The areas of fintech I get most excited about include data exchange and enrichment; companies providing the orchestration layer to manage and drive insights from the multitude of applications and point solutions that exist in an enterprise; fraud and identity management; and agile billing platforms that enable companies to be flexible and responsive in their pricing models. I’m also passionate about the ability for technology to unlock financial literacy, and products for those who have traditionally been underserved. I like products that are emerging to prevent people with low incomes from getting trapped in endless debt cycles.

‍What should founders know about me?

When I sit on your board, my role is to engage in candid, constructive dialogue that propels your company forward. I bring a holistic perspective to the challenges and opportunities facing your business. Whether it's connecting you with the right talent or customers, I'm all in. But I will never shy away from telling you what I really think. It is this transparency that has helped me create long lasting relationships with founders I’ve backed over the last two decades.

And yes, I may be intense but I am far from robotic. The humanity in business matters to me a lot. Whether it's dealing with employees or investors, people are not just line items on an income statement; they're the essence of any successful endeavour.

‍Despite the fact that my finance career began in the late nineties it was a different era. I was regularly the only woman in the room. And was referred to as ‘sweetheart’ more often than I care to admit. As a result of this - and the fact that I am raising a child with a physical disability - it has been important to me throughout my career to ensure that wherever I work we are creating space for diverse voices to get heard. 

‍While I'm a strong advocate for Canadian talent, my love for languages and diverse cultures runs deep in my DNA. This blend of local pride and international vision defines me, both as a person and an investor. 

Very impressive. I think OMERS Ventures has found itself an exceptional leader, and I do wish her a lot of success.

I've seen it all in venture cap: the good, the bad and downright ugly (I was at BDC in 2008, VC got massacred).

It's not an easy game but necessary and can be lucrative (just look at OTPP's success with SpaceX, and soon Anthropic and other companies in its portfolio, including Harvey, the leading AI legal platform). 

For it's part, OMERS Ventures has done very well with Xanadu despite that stock's recent selloff. 

Its Canadian focus comes at the right time but there is competition in the space.

I recently covered the Canada Investment Summit where I noted Radical Ventures launched Canada’s largest AI fund with $1-billion USD first close and lots of top Canadian pension funds backing it.

I said Canada's VC industry desperately needs major capital and expertise to nurture startups into mature growth companies. Hopefully this new fund will be a huge success.  

I wish the same for OMERS Ventures as Laura Lenz takes over the helm.

Just remember, venture cap is never an easy game; you can allocate $5 million or more to 100 companies and are lucky if one or two hit a home run (or grand slam like SpaceX). 

This is why pension funds typically allocate between 1 and 3% of their total assets to venture cap/ growth equity. 

Alright, let me wrap it up there.

Below, from two years ago, the kickoff CIX Summit with Co-chairs Laura Lenz, (then) Partner at OMERS Ventures and Alison Nankivell, Senior Vice President, Fund Investments at BDC Capital, discussing the current state of the Canadian market, venture capital investing, and the future of the Canadian tech landscape. Great insights from both of them.  

Consequences of austerity: How reductions in BLS funding threaten the credibility of our statistics

EPI -

Key takeaways

  • Years of government funding cuts are undermining the U.S.’s position as a global leader in providing the reliable statistical information that businesses and policymakers need for sound decision-making.
  • The Trump administration has accelerated the funding cuts and worked to degrade the effectiveness and independence of data-collecting agencies.
  • The Bureau of Labor Statistics (BLS) is a prime example of an agency whose data collection in areas like employment and wages is integral to our understanding of the economy’s health and whether it is heading into a recession.
  • A decline in response rates to one of the BLS’s key surveys was already underway but, absent funding increases and survey modifications, it will be harder for economists and policymakers to make timely sense of changes in the labor market.

Historically, the U.S. has been a leader in providing reliable and timely statistical information to support business strategy and policymaking. The value of information provided publicly and free of charge to businesses, households, and governments is immense. Yet underinvestment over the past 15 years is a key reason why the U.S. lost its position on the cutting-edge of public statistical services worldwide.

Since the beginning of the second Trump administration, this underinvestment has accelerated, and the administration has made intentional efforts to degrade the effectiveness and independence of the federal statistical agencies (FSAs). This accumulation of threats to the effectiveness of the FSAs will rapidly degrade the value of the key public good they provide, unless policy changes course sharply.

This blog post provides just one example of how cumulative underinvestment has blocked the ability of a key FSA to respond to developments, making its data less reliable over time. The Bureau of Labor Statistics collects a range of necessary data tracking the performance of the U.S. labor market. This BLS data are a key input into high-stakes decisions across the U.S. economy—including for both public and private actors. For example, the Federal Reserve relies on BLS data about unemployment rates, payroll job growth, wage growth, and price indexes to set monetary policy. The more volatile the BLS data are from month to month, the worse the information that guides Federal Reserve decisions.

Private industry also relies heavily on these statistics. A 2018 survey conducted by the National Association for Business Economists found that 95% of businesses responded “yes” to the question: “Are government data important for analyses and forecasting that drive business decisions?” Employment and unemployment data produced by the BLS were rated as the most important data source for informing business decisions.

Yet over the past 15 years, the BLS has gradually lost personnel and funding, which has been undermining their mandate of producing timely, accurate statistics on wages, prices, and the labor market. More recently, the Trump administration’s choices to freeze BLS hiring has further strained Census field staff charged with collecting household survey data. Worst of all, the Trump administration took the unprecedented step of firing the commissioner of the BLS simply because the agency accurately reported data that the administration happened to find politically inconvenient.

Even without further blatant political pressure on the BLS’s independence, the agency will encounter growing difficulty in doing its job effectively in coming years. One of their most important efforts is the fielding of the Current Population Survey (CPS), a survey of thousands of households across the U.S. taken every month, which provides detailed employment and wage information. The CPS is the source data for the monthly estimate of the nation’s unemployment rate, for example. This is in turn a key criterion for assessing whether the economy is heading into recession. In recent years—after the COVID-19 pandemic—the response rates for the CPS have sharply declined. These declines, if not countered with greater investment in response rates, may make it harder for economists and policymakers to make timely sense of changes in labor market, particularly for populations that already have small sample sizes, such as rural areas or detailed demographic groups.

The rest of this blog post highlights the problem of falling response rates, demonstrates that they have made some labor market measures more volatile month to month, and shows that these falling response rates have occurred over the same period as the retrenchment in resources for the BLS.

Nonresponse reduces sample size in the Current Population Survey

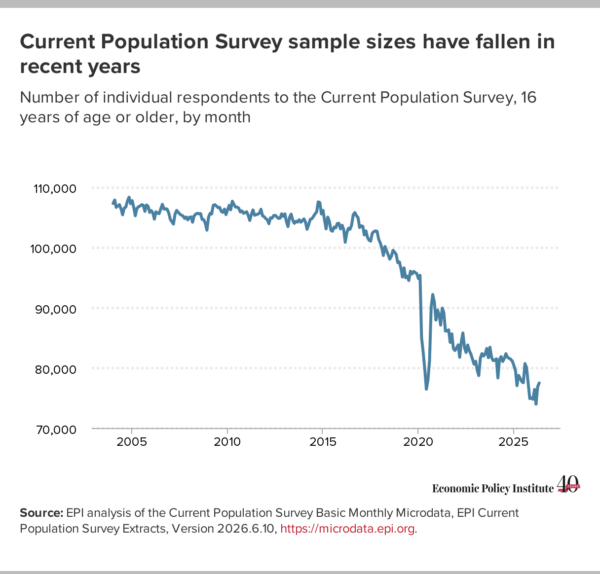
The Current Population Survey asks questions about employment and other labor market characteristics to 60,0000 households or about 110,000 individuals every month. Between 2005–2016, the Current Population Survey household survey was able to steadily receive responses from around 107,000 people, ages 16 and older. However, as noted by others and shown in Figure A, the number of households responding to the survey has declined since the mid-2010s and then fell precipitously after the COVID-19 pandemic. In the first few months of 2026, just over 75,000 individuals, ages 16 and older, had responded to the monthly CPS.

Figure AFigure A

The decline in response rate has likely occurred for a few reasons. The Bureau of Labor Statistics notes that the rate of refusals had been increasing as early as the 1990s, likely as the world became more connected with computers and the internet, leading to less reliance on in-person interactions to conduct business. Social trust has also gone down over the past few decades, and the share of adults who agree that “most people can be trusted” has decreased by more than 15% since 1984.

More recently, the COVID-19 pandemic, coupled with concerns for privacy and distrust in the government, may be the reason that the rate of decline grew in recent years. The COVID-19 pandemic forced many workers to transition to remote work, and concerns about contagion limited overall social interactions, making response collection increasingly difficult. Additionally, concerns about privacy or retribution from the state felt by groups like immigrants may make some people more reluctant to answer questions for fear of deportation. 

Finally, distrust in the federal government, fueled by recent overtly political activity, could be behind some of the reduction in response rates. For example, when the Bureau of Labor Statistics published two consecutive months of large negative revisions to the number of payroll jobs in mid-2025, the Trump administration leveled charges—which were baseless and never backed up by any evidence—that the BLS had manipulated the data for political purposes and fired then Commissioner Erika McEntarfer. People are less likely to trust government if they think publicized information and facts are politically motivated. 

Smaller sample sizes are linked to less precision in key labor-market estimates

If the size of sampled households is large enough, declining participation does not have to significantly affect the reliability of statistics produced from the survey. However, if declines in participation reduce usable sample sizes too much, this can lead to estimates with less precision, which can reduce researchers’ ability to parse a signal from statistical noise in a timely manner, especially for economically vulnerable groups.

For example, because the unemployment rate for Black workers is volatile, it can be difficult to accurately diagnose labor market softness for this group. If the sample size is too small to generate statistical precision in each month, researchers will require increasingly more months of data to be able to diagnose labor market softness, which could jeopardize the timeliness of proper policy responses to support the labor market.

Every month, the Bureau of Labor Statistics publishes statistical significance summary tables, identifying whether changes in labor force indicators are statistically significant at the 90% level. BLS publishes these statistical significance tests for dozens of indicators across several demographic groups, including for Black workers. We collected these tables over time and documented the margin of error needed in order to claim a 1-month change in unemployment was statistically significant, shown in Figure B.

While the margin of error that is needed to claim a change is statistically significant varies with the level of unemployment rate, the reduction in precision from lower response rates is evident when we hold the unemployment rate constant. The two red lines in Figure B identify the effect size needed to claim statistical significance for a change from a starting unemployment rate of 7.3%. In November 2017, when the sample size of the labor force was 63,346, a 0.66 percentage point change in unemployment would have been considered a statistically significant change. In April 2026, when sample size of the labor force decreased to 45,416 respondents, a 0.84 percentage point change in unemployment is required to claim statistical significance.

If the declines in survey participation are not random across the U.S. population, estimates may also be biased, which runs the risk of conveying inaccurate information about the state of the economy. For example, if nonresponse is more likely to occur among unemployed respondents compared with employed respondents, the statistics derived from these samples may suggest labor market softness when there is none. These concerns are already materializing: The Census reported that nonresponse had biased income statistics from the CPS Annual Social and Economic Supplement upward by 2%–3% since 2020.

Researchers and field staff at Census and the BLS are aware of potential concerns of bias in their estimates and do their best to weight estimates using population counts from administrative data and other sources so that these issues don’t happen. However, if sample size declines continue on this trajectory, the BLS will need to create new methodologies and sampling strategies, all of which will require funding.

Steady throttling of BLS funding makes all decision-makers—public and private—less well informed

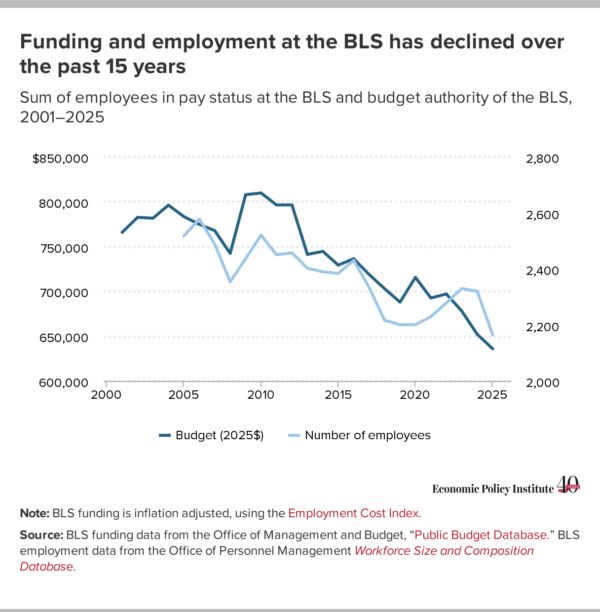
The declining precision of estimates in the Black unemployment rate is just one of the key indicators affected by a BLS that lacks resources to respond effectively to growing data collection challenges. Achieving a larger sample size for key surveys requires a well-functioning and well-funded BLS with personnel who can take on the challenges of administering surveys in the 21st century. Yet this is the exact opposite of what is happening. Figure C shows that from 2005 to the present, the staffing at the BLS went from roughly 2,500 employees to just over 2,150, a drop of about 15%.

Figure CFigure C

Funding has followed a similar trajectory. Since its high-water mark in 2010, the BLS budget has declined from $810 million to $636 million in inflation-adjusted terms, a decrease of 20%. These cuts don’t hurt just the estimates generated by the Current Population Survey. In the past couple of years, the BLS has been forced to reduce data collection for the Consumer Price Index and to discontinue certain Producer Price Indexes in an effort to cut costs. At a time when affordability and price changes are top of mind for U.S households and businesses, depriving public and private decision-makers of accurate and timely information about prices makes little sense.

Increased funding would allow the BLS to maintain all their current functions and implement new procedures to address declining sample sizes. In 2023, BLS began to modernize the collection process of the CPS to improve response rates by allowing online self-completion of the survey and other collection process improvements for certain data products. This BLS initiative is happening in parallel to similar initiatives in several other countries undertaking modernization efforts. The United Kingdom, the Netherlands, Australia, and Canada have all received funding to launch similar modernization efforts for their own household surveys to address declining response rates. However, the BLS requests for increased funding for the modernization efforts have not been fully granted.

The decision to steadily defund the BLS is especially striking when weighed against the large economic benefits provided by the agency and other federal statistical agencies. The BLS provides up-to-date precise estimates of economic indicators that policymakers and business leaders alike rely on. Previous research finds that increased economic uncertainty can have negative effects on the economy, proving the important role that the BLS plays. Moreover, some economists have estimated in 2025 that the BLS generates economics benefits of about $25 for every $1 spent on the agency’s budgets. The 2025 FY BLS budget was approximately $636 million, meaning the BLS currently generates about $15.9 billion in economic benefit. Across all agencies, in FY 2022, the combined budget request for statistical agencies was $7.1 billion or 0.3% GDP, yet the benefits have been measured to be around $770 billion.

Conclusion

At a time when more information on the economic and social well-being of people and communities is needed, not less, funding the BLS should be a top priority. Addressing nonresponse will require substantial effort and creativity to counteract declining levels of social trust and anti-government sentiment. It will, for example, require public campaigns to convey that information provided to the BLS is confidential and safe, and changes in methodology to render the correct statistical adjustments, such that the statistics generated are unbiased. 

Rather than tackle these challenges head on however, the Trump administration put forward a proposal that would reduce the number of statistics about rural and less populous substate areas that could be published without running the risk of disclosing personally identifiable information. These proposals are a lazy solution to the real but solvable problem of making public data widely available and fully confidential. They would provide less information on the economic and social well-being of citizens, likely leading to delays in accurately diagnosing economic and social problems.

When agencies like the BLS are underfunded and understaffed, they aren’t able to conduct the critical functions of their agency or serve the public to the degree their mission entails. Funding for these organizations shouldn’t be up for debate, given how strong of an economic benefit they deliver.

Why Are Pensions Funds Slow to Adopt AI?

Pension Pulse -

Josh Welsh of Benefits and Pensions Monitor reports plan sponsors move slowly on AI despite efficiency promise:

Despite all the noise that AI is making in pension and benefits administration, several experts suggest its presence is smaller and more cautious than the hype suggests.

According to Sean Liss, investment consultant at HUB International, AI adoption among plan sponsors has been uneven. Yet, while strategy-level use remains thin, record keepers have started applying generative AI to improve member-facing platforms, making benefit sites easier to navigate and investment content more digestible.

The goal, from a plan sponsor's perspective, is driving engagement and financial literacy among members, though Liss cautioned the technology is still finding its footing.

"It's still a work in progress, but they're making a little bit of ground there," he said.

Gen AI could simplify outdated pension plan sites

"Right now, we're in an age where attention spans are pretty short and pension plans want their members to be educated on their plan. That’s either through understanding their risk tolerances or the investment options that are available to them. But the sites aren’t always easy to navigate," said Liss, adding generative AI could close that gap by simplifying site layouts and making investment content more accessible, which in turn could boost member engagement and plan literacy.

"Those are all things that plan administrators want to see," he added.

Faulty AI output threatens plan member trust

Meanwhile, Sebastien Betermier, finance professor at McGill University and executive director at International Centre for Pension Management (ICPM), identified three AI applications gaining traction in pension administration. The first is automating the note-taking and debriefing process during member calls, allowing engagement officers to cycle through requests faster and maintain a searchable record of interactions. The second is deploying AI-powered bots to field routine member questions without tying up staff.

But the third, he suggests, is trickier because it's not about using AI at all. It's about controlling what AI tells plan members.

"Oftentimes pension funds will find that their members get their information from elsewhere like a social group or social media or AI aggregators but the information is not necessarily correct and that’s dangerous because by then it’s too late," said Betermier.

"What's doubly dangerous is if you have social media picking up on a fund acting and the information is not necessarily correct, but then I come in as another member and I use ChatGPT to say what goes on in my fund because I know they'll quickly summarize and get the information. The aggregated information may actually be wrong,” he added, noting that leaves funds racing to ensure their own content is what AI tools surface first because members "might not even come to the website. They might only interact with their own AI machine," said Betermier.

"This is more making sure that in the age of AI, members are getting the correct information from you in a way that is efficient, but in a way that doesn't just create all kinds of weird rumors, and then everything gets bypassed," Betermier added.

Liss agreed, flagging faulty AI output as one of the biggest risks facing the space right now. Fiduciary responsibility, he noted, doesn’t shift when plan administrators delegate tasks to a record keeper or an AI tool because accountability stays with the plan.

Yet, that concern laps onto a broader worry both speakers share: trust.

"The biggest asset a pension fund has is trust above and beyond the assets it actually does manage. If you lose trust, you lose a lot of credibility in the eyes of the member," said Betermier.

While Liss expects AI integration to accelerate, he underscored that organizations need to understand both the risks and the fact that liabilities remain theirs regardless of what technology sits between them and the member.

AI efficiency gains hinge on governance and liability

Still, Betermier suggests the expected productivity gains from AI are real, but only if the implementation is handled with proper governance and data protections in place.

"I think AI has profound effects because it can make us much more efficient at several tasks that used to take more time. It has to be done really well. You cannot move too fast into it. I know funds are taking their time to make sure that it's done well," said Betermier.

Liss agreed that while AI will drive efficiencies, he argued its limits are baked into the nature of the work, particularly as "AI doesn't have emotion and emotion has a role in investing as well and making people comfortable with the decisions that they're making," he said.

On the consulting side, he sees potential in making quarterly reports - covering industry trends, economic data, and fund performance - more accessible to HR leaders, CEOs, and CIOs who oversee pension plans. For instance, he points to features like clickable definitions or scannable term explanations could replace the need to dig through an appendix.

He expects AI to eventually help with drafting member communications and consolidating information on the administrative side but emphasized that anything resembling advice should stay out of AI's reach.

Still, he draws a parallel to the early internet, which expanded access to information without eliminating the need for human judgment. He expects AI to follow a similar path.

"There'll always be a need for the human perspective," he said. 

It's a slow week in Pension Land so let me cover this topic which Sean Liss and Sebastien Betermier cover well.

I'm by no means an AI expert -- far from it -- but like any other tool in the pension toolkit, if it's used properly, it can add significant value on several fronts: asset management, pension administration, communications, finance, legal, IT and sustainable finance.

But it's still early days in the AI world and adoption, and while implementation is critically important, from a governance standpoint, it presents all sorts of risks.

There is no point in rushing it through, as AI models are changing from month to month. 

You can have test pilots in various sections of your pension plan but you need to measure outcomes properly and make sure there is value added.

Having said this, I see how AI can enhance productivity from an investment point.

This morning, I had an exchange with an investment advisor who uses Claude to screen stocks, using parameters he specifies.

I said to him I wish I can use Claude to go through my top funds' quarterly activity and then use my weekly and daily chart parameters to see which ones are making meaningful breakouts.

He took a handful of biotech and cybersecurity stocks I mentioned and then ran them through his parameters and sent me a report.

Of course, I then have to pull the trigger or not, but it's an amazing tool when used properly. 

I asked him if everyone starts using Claude, will alpha disappear and he replied:

No, but it will move. What disappears is the alpha that comes from processing public information faster or more thoroughly than the next person. What survives, and may even grow, is alpha rooted in things a model can't hand to everyone equally. Sure, news, earnings reactions, filing, etc gets in the universe more faster. What doesn’t disappear is the advisor alpha. Proprietary info, behavioral edges and judgment especially on novel situations will prevail.

So no, AI will not replace portfolio managers or analysts; it will help them become more productive at their work (the same for doctors, lawyers, accountants, etc.).

You still need brains and human judgment and interpretation.

But how you implement and adopt AI and measure outcomes across pension funds is critically important.

I keep coming back to this and unfortunately, many pensions don't even have an AI strategy or roadmap.

Anyone can say "we look at the risks and opportunities of AI" but what does that mean in practice and how are outcomes measured?

Below, as pension plans face growing pressure to adopt AI, many are pausing to ensure it’s implemented with the right governance and fiduciary oversight. This 45-minute discussion from the Berwyn Group explores both the opportunities and the risks, with a focus on practical, real-world application.

More Perspectives on the Canada Investment Summit

Pension Pulse -

Barbara Shecter of the National Post reports pension CEOs at home and abroad hail summit as positive starting point:

Global investors that came to the Canada Investment Summit over two days in Toronto this week did not pour money into the 167 project touted the deal book presented, but the head of one of Canada’s largest pension funds says many left armed with the intention to do more in this country.

“I think if you came expecting to leave with a project in hand, you’re probably over-optimistic … (but) I judged, from the people I spoke to, that most people left with a really positive inclination towards coming back to do more,” said Jo Taylor, chief executive of the $303.2-billion Ontario Teachers’ Pension Plan Board.

“There are enough real projects around to keep good momentum on the nation-building concept, and actually demonstrating to local and international investors there’s something to do now.”

That was true for Annette Mosman, chief executive of one of Europe’s largest pension funds, APG Groep N.V. of the Netherlands, which has €639 billion under management.

In an interview on the sidelines of the summit, she said she learned about projects in sectors that interest her fund and at a size and scale that warrant further due diligence.

“The overarching themes like defence, energy, digital — we recognize them completely from a European perspective,” she said. “I think Canada now is a bit quicker compared to Europe, making it more tangible.”

In particular, she cited Prime Minister Mark Carney’s conviction to make Canada an energy superpower and his announcement Tuesday that the federal government plans to invite pension funds to invest tens billions of dollars in the country’s four largest airports.

“There are more concrete investible assets, so the conditions are better,” she said. “There are concrete investible assets of relevant size if you look at companies like ours with (hundreds of billions of euros in) assets under management.”

APG has some investments in Canada, including a $328-million stake in Hydro One purchased on behalf of pension fund ABP, and Mosman said she met the utility’s CEO, Megan Telford, at the summit.

She declined to put a timeline on when APG might invest more money into Canada, and added that some of the projects of interest aren’t yet sufficiently concrete.

“We have conditions,” Mosman said, adding that, like all pension funds, hers has a duty to assess risks and to protect the funds that belong to pensioners.

“Our teams can look at the projects, our teams can talk with Canadian pension funds, and then do their analysis like we always do,” she said. “We don’t do politics, so … whether it’s defence, whether it’s digital or energy, it’s depending on the structure, it’s depending on the governance, it’s depending on the returns.”

Mosman APG is hoping to make investments that have attributes like Hydro One: predictability in a regulated environment, stable cash flow and a long-term horizon.

“That fits our liabilities and what’s good for the pensioners, and I heard a lot of examples (like) that,” she said. “Airports is also an example of such infrastructure.”

She said the U.S. is a very good market for her fund and will remain so, but she is increasingly looking at Canada as distinct from its southern neighbour.

“We are diversifying. We always have been diversifying globally (but) maybe have seen North America as one market, and I think that’s changing,” she said. “So it’s now Canada and U.S, and the risks are different in the U.S. Having heard today what Canada can deliver or may deliver, I think then it will add up to better opportunities.”

Mosman said she already has ties with Canada’s business community through the Hydro One investment and with Canada’s pension executives who, she said, share a similar culture with the Dutch fund. They have already worked together outside Canada. In 2020, for example, APG and Canada Pension Plan Investment Board participated in a $1-billion joint venture with ESR Cayman Ltd. to invest in and develop an industrial and warehouse logistics portfolio in Korea.

Recent pledges by Canadian pension funds to bump up their investments in Canada could provide further co-investing opportunities for her fund in this country, she said.

“We do that already, but more abroad in other countries,” she said.

The summit also provided a deeper opportunity to meet with provincial premiers and learn about additional projects within their jurisdictions, Mosman said.

John Graham, chief executive of the Canada Pension Plan Investment Board, one of the co-hosts of the summit, said that is exactly what the gathering, organized by the federal government alongside CPP Investments and PSP was meant to achieve.

“This is not like a trade fair where people are going to go and buy tires or something,” he said “These are big, complicated transactions…. This is about long-term investing, getting the right capital into the country.”

He said the summit was also a showcase for many Canadian corporations, including energy and mining firms, which could benefit from exposure to global investors.

“From an investor perspective … sometimes the easiest way to invest in a country is through the public markets,” he said.

“They can buy their shares, they could buy their debt, and then if you have companies that are very capex intensive, they can help support that through various means, through debt, equity, or some other form of capital.”

Graham said the nuts and bolts of getting a deal done is often underestimated, particularly when it comes to infrastructure.

“We’ve been investing in infrastructure for almost 20 years around the world. These are big, complicated investments,” he said, adding that there is often a government component to contend with as well.

“You have to do it right, and you ultimately have to land on something that’s win-win for everybody.”

On Tuesday, CPP Investments and Brookfield Asset Management Ltd. announced a $50-billion Maple Fund to make large-scale investments in critical infrastructure and strategic industries across Canada over the next five years.

Graham said although it was announced on the final day of the two-day summit, it has been in the works much longer.

“We’ve been working on opportunities with them, and we had this idea quite a while ago, long before the summit,” he said. “It gives us access to a best-in-class partner, and, for Brookfield, it gives them opportunity to basically raise funds … or to use the funds they have.”

The Maple Fund will target project values of greater than $5 billion in equity capital, and was designed to allow other investors to partner with the pair on individual investments to further expand the capital available.

Last week, PSP and the Ontario teachers’ pension plan both announced a bump in domestic investments in the coming years.

Taylor said the decision at Teachers’ to invest an additional $10 billion in Canadian public and private markets by the end of 2027 and to announce it both felt like the right thing to do.

“This wasn’t forced on us. It was actually something we chose to do, and we chose to do it because it’s the right time to say it,” he said, noting that the new investments will come on top of about $100 billion that the fund has already invested at home.

“Why hold it back if you’re going to make that investment? Why not be positive and actually very much assertive that this is the right thing for us.” 

I already covered the inaugural Canada Investment Summit last week here, but I like the perspectives in this article from domestic and foreign pension fund CEOs.

OTPP's CEO Jo Taylor said people who came expecting to leave with a project at hand were over-optimistic but they let with a positive view of the summit and future opportunities.

I'm not going to lie, I was expecting some more big announcements on privatizing assets, especially airports, but I guess we will have to wait for the massive bureaucratic machine in Ottawa to get things going (pretty sure Michael Sabia is on that).   

CPP Investments' CEO, John Graham points out that for many investors, the easiest way to invest in a country is via public equities and bonds.  

Obviously, the larger a fund is, the more risk appetite for large private market assets.  

Annette Mosman, CEO of APG (featured at the top of the post) which already has a big stake in Hydro One, was very explicit in stating that they're looking for the right conditions to invest in Canada, namely, in assets that fit their liabilities and she mentioned airports.  

Anyway, the Summit is over, now comes the hard work ahead of execution and delivering projects that domestic and foreign investors are looking for.

I agree with everyone who says what comes next is critically important. 

If we wait another year to announce projects, it would be a grave mistake.

As James Bradshaw of The Globe and Mail notes, the Summit attracted all the right people, but will it bear fruit? That remains to be seen.

At the end of the day, it's all about outcomes. That's my measure of success.

So, I agree with John Mckenzie who rightly notes Canada must turn investment summit momentum into certainty and execution. 

Lastly, on October 22, PSP Investment's CEO Deb Orida will be joining Goldy Hyder, CEO of the Business Council of Canada, for a timely conversation about Canada’s investment moment and what comes next:


That should be an interesting discussion. 

Alright, let me wrap it up there.

Below, Canada's first ever Investment Summit being held in Toronto this week, was a message to global investors that Canada is open for business and ready for the big leagues. Canada's largest pension fund already plays there. John Graham is the CEO of CPPIB, the investment arm of Canada Pension Plan. 

On this episode, he speaks with host Amanda Lang about the opportunities Canada needs to show the rest of the world. Listen carefully to his insights.

Pages